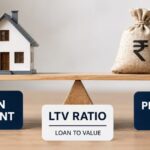
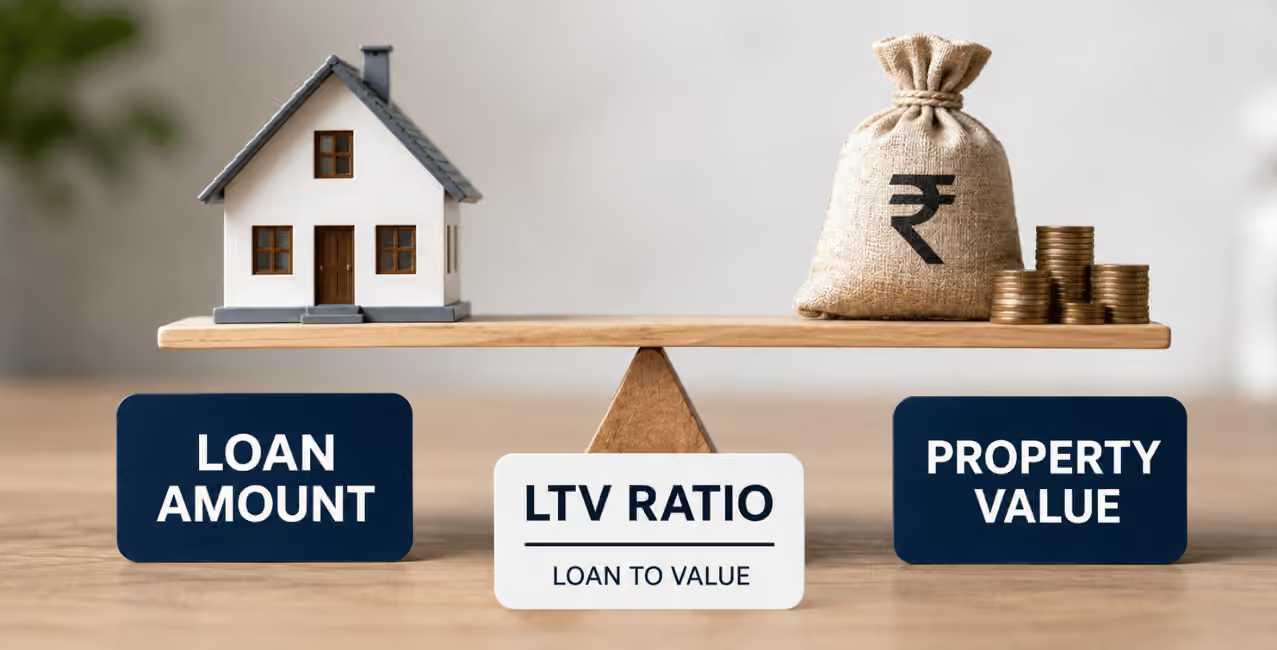
A property valued at €500,000 secures a €300,000 loan. On paper, that leaves €200,000 between the loan amount and the valuation. The calculation is straightforward. Understanding what that margin means requires more detail: how the property was valued, whether construction is complete, and how much debt the property actually secures.
When reading a profitus review, look beyond the headline LTV figure. Check whether the valuation reflects the property’s current condition or its expected value after construction, how much debt is secured against it, and which lenders would be paid first if it were sold following a default. These details help explain what the collateral could cover if the borrower fails to repay.
How Loan-to-Value Is Calculated
Loan-to-value, usually shortened to LTV, expresses borrowing as a percentage of the property’s assessed value. Dividing a €300,000 loan by a €500,000 valuation produces an LTV of 60%.
In this simplified example, the property’s stated value exceeds the loan by €200,000. That difference provides a margin against a fall in value, although it does not establish what investors would recover if repayment failed.
The ratio is also sensitive to changes in either number. If the loan stays at €300,000 but the property’s value falls to €400,000, LTV rises to 75%. No additional borrowing is needed for the relationship to change.
Which Property Value Is Being Used?
A finished apartment building and a construction site represent different stages of the same project. A valuation based on completed apartments assumes that the remaining work has been carried out.
Consider a fictional development with a current valuation of €400,000 and an estimated completed value of €700,000. Against a €280,000 loan, those figures produce ratios of 70% and 40%, respectively.
Both calculations are mathematically correct, but they describe different conditions. The second relies on reaching completion. It therefore needs to be considered alongside the remaining construction budget, funding arrangements, and timetable.
A project listing becomes easier to interpret when it states the valuation date, the property’s current condition, and any assumptions about future work.
What a Lower Sale Price Would Mean
The valuation is an estimate. A hypothetical recovery calculation can show how changes in the eventual sale price would affect the available funds.
Return to the €300,000 loan secured against a property valued at €500,000. Suppose the property sells for €350,000 and selling and recovery costs total €25,000. That leaves €325,000 before considering interest or any other claims.
If the sale instead produces €300,000 with the same costs, the remaining amount is €275,000. Under the simplified assumption that this is the only debt requiring repayment, there would be a €25,000 principal shortfall.
These figures are illustrative rather than a prediction about any particular project. They show why a difference between loan amount and valuation cannot be treated as a guaranteed recovery amount.
One Funding Round May Be Part of a Larger Loan
Property developments may seek financing in stages. A listing for a €100,000 funding round therefore needs context: it could represent the project’s entire borrowing or an addition to existing debt.
Imagine a property valued at €600,000 with €250,000 in outstanding debt against it. A further €100,000 would bring total borrowing to €350,000, equivalent to approximately 58.3% of that valuation.
Calculating only the new round against the property value would produce 16.7%. That figure would omit the earlier borrowing.
The financing schedule should make the relationship between individual rounds and total secured debt understandable. Check which lenders have priority over the sale proceeds.
How the Borrower Plans to Repay
LTV describes the relationship between debt and collateral. The repayment plan explains where the borrower expects to obtain the cash.
For a fictional apartment development, repayment might depend on completed sales. The relevant milestones would include finishing construction, securing buyers, and receiving their payments. For a refinancing project, the key event might be approval and drawdown of a replacement loan.
Progress reports should show whether the borrower is on track to repay. If construction falls behind or refinancing is delayed, an update should explain the effect on the repayment timetable. A current valuation, a clear account of outstanding debt, and evidence of progress toward repayment allow investors to assess the project beyond the percentage shown on its listing.